
TRW & Co · Real Estate, Projects & Energy
Project Finance in Singapore

Project finance in Singapore funds power, energy transition, data and infrastructure assets on the strength of their own contracts and cash flows. Lenders need bankable offtake, fixed-price construction, a perfected security package and direct agreements that allow step-in. Singapore is also where much of the region's project debt is documented, booked and, when disputes arise, arbitrated.
Key pointLenders lend against the contract web, not the asset: a PPA whose tenor, termination payment or change-in-law terms do not match the debt will cut debt sizing more than any financial covenant.
At a glance
Charges within 30 days
Charges created in Singapore must be registered with ACRA within 30 days; an unregistered charge can be void against a liquidator and other secured creditors.
Licence by unit size
Grid-connected generating units below 1 MW are exempt; 1 MW to below 10 MW need a Wholesaler Licence; 10 MW and above need a Generation Licence.
Ipso facto restriction
Section 440 of the IRDA limits termination of contracts merely because a company enters certain restructuring proceedings, affecting lender and offtaker rights.
Carbon tax in models
The carbon tax is S$45 per tonne for 2026 and 2027, so change-in-law and carbon cost allocation matter in PPAs for fossil-fuelled assets.
Regional import pipeline
Singapore targets about 6 GW of low-carbon electricity imports by 2035, through EMA's staged Conditional Approval and Conditional Licence process.
Swipe or scroll →
What project finance in Singapore covers
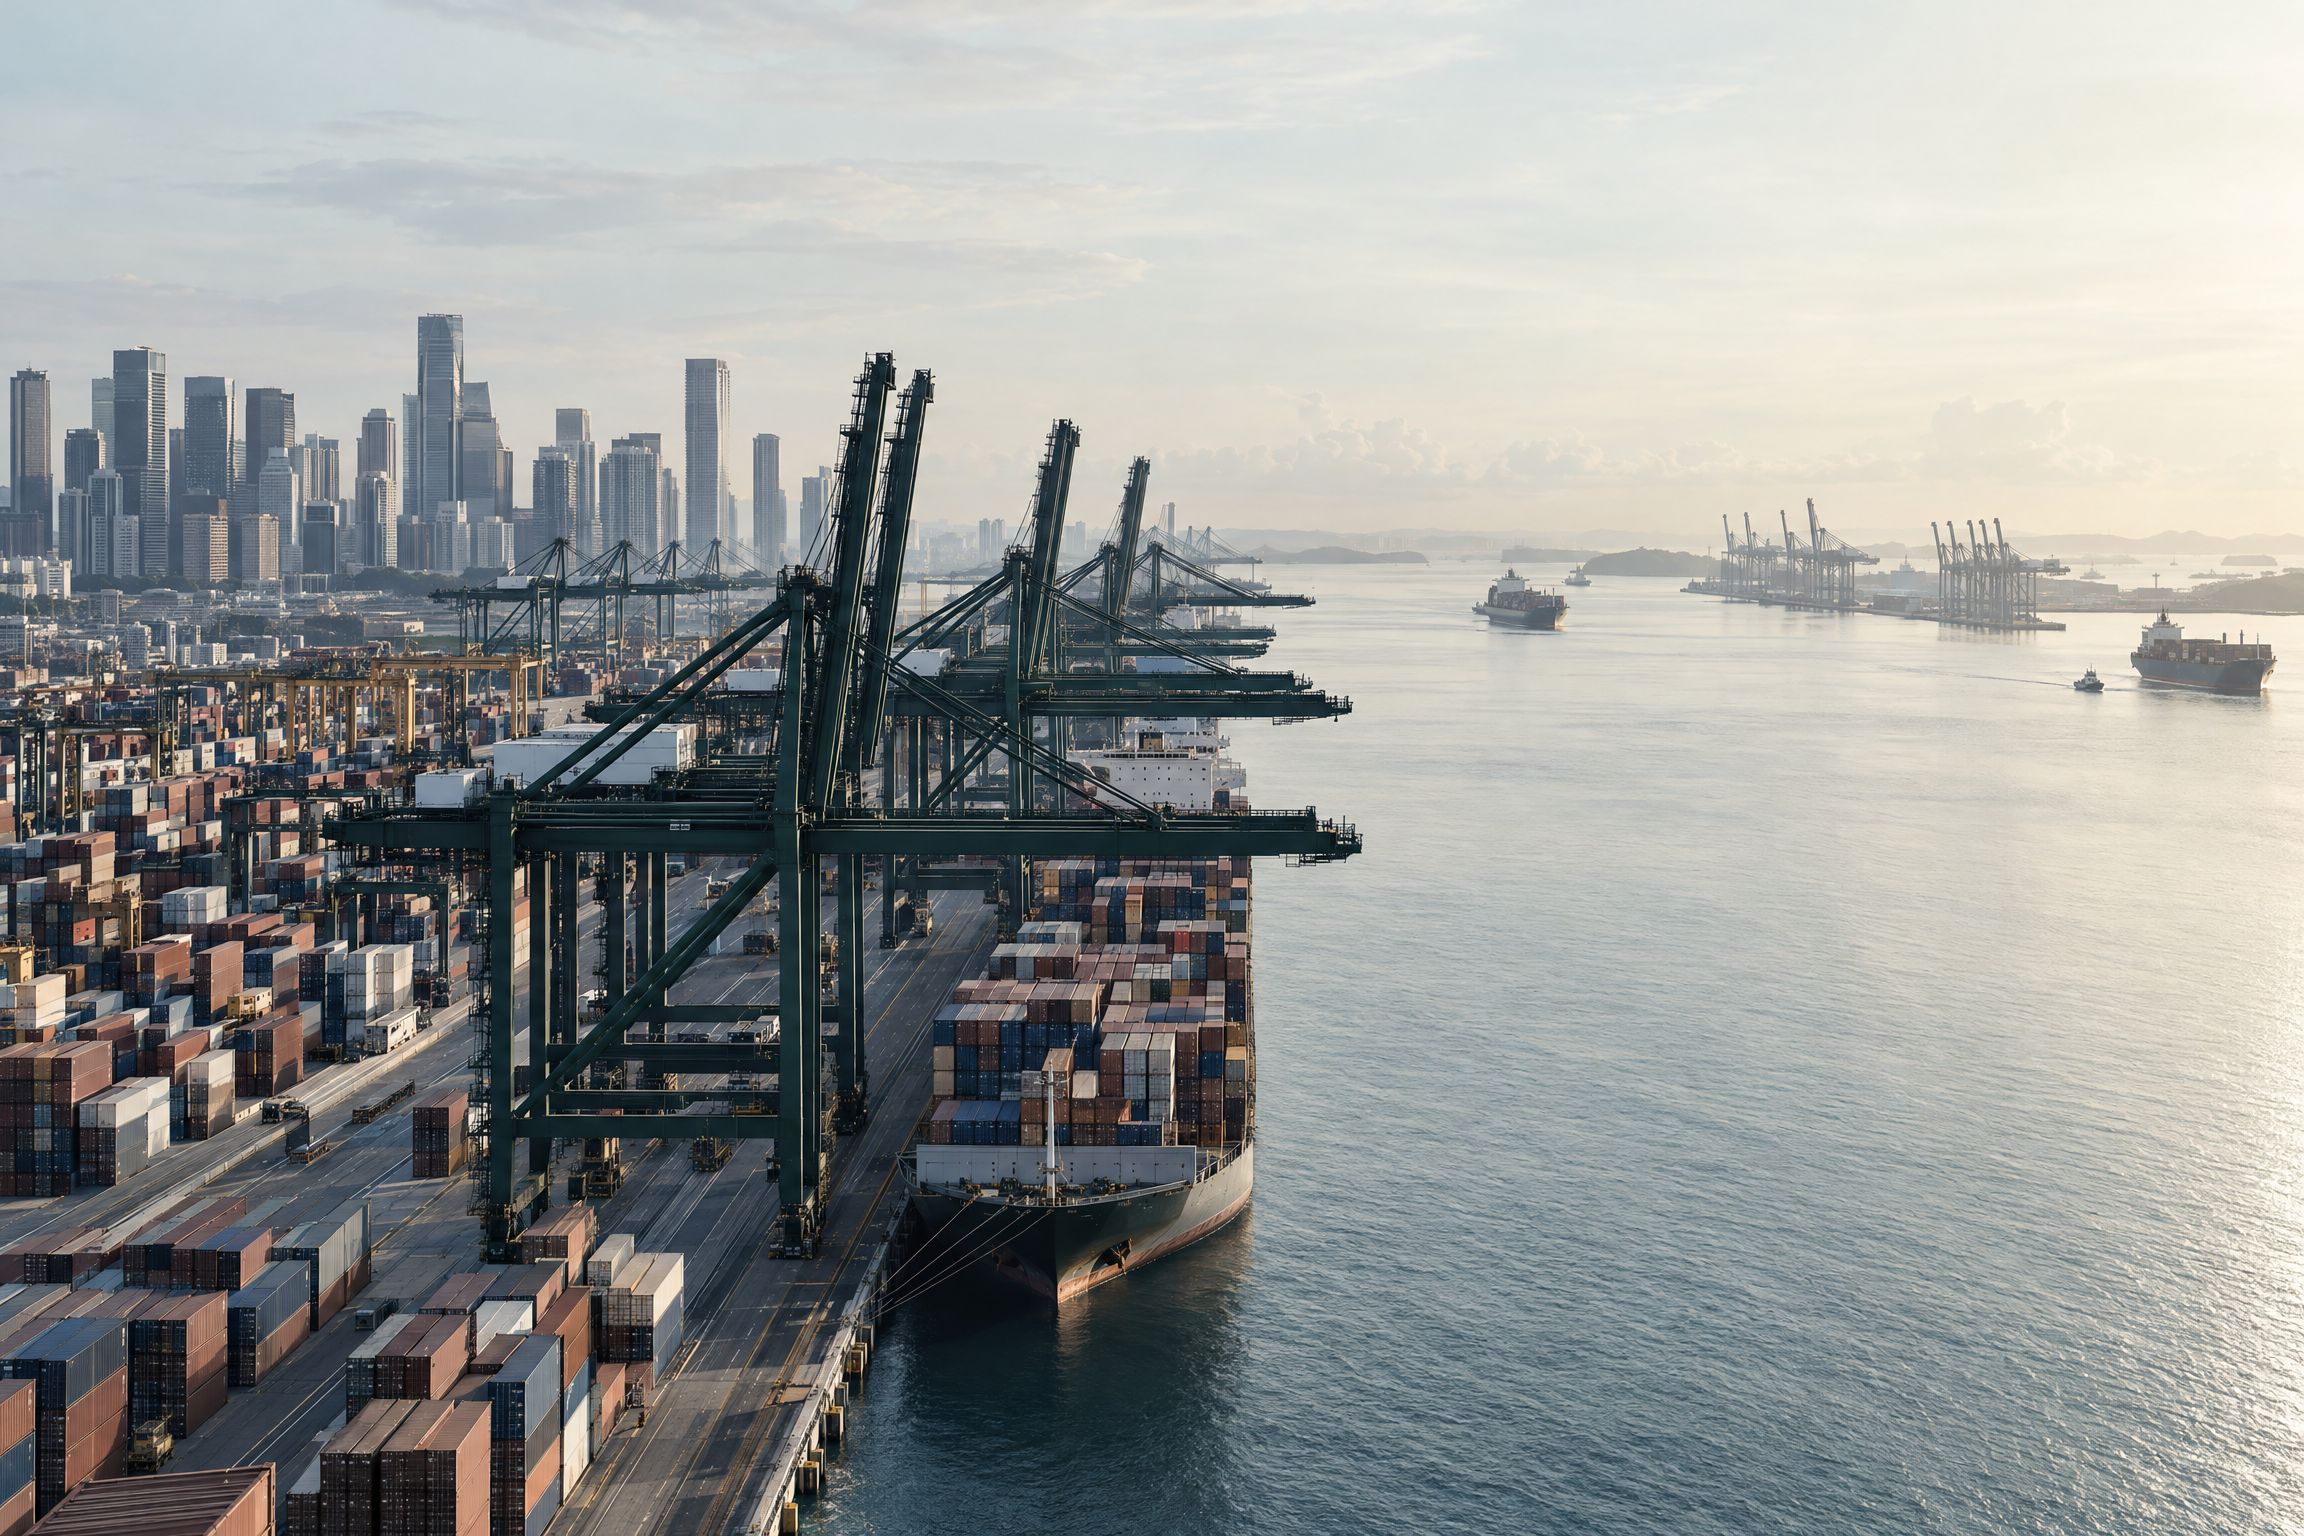
Project finance in Singapore is lending to a single-purpose project company where the lenders look primarily to the project's own cash flows, contracts and assets for repayment, rather than to the balance sheet of its sponsors. It funds power plants, solar portfolios, battery storage, data centres, waste-to-energy and water plants, ports, transport assets and, increasingly, cross-border renewable energy and interconnector projects.
The legal work is different from ordinary corporate lending. Because recourse to sponsors is limited, lenders need the whole contract structure to be bankable: a creditworthy offtaker paying for output, a construction contract that delivers on time and on budget, operating arrangements that keep the asset available, and security and direct agreements that let lenders step in before the value disappears.
Singapore plays two roles. It hosts domestic projects that need financing under Singapore law, regulated by agencies such as the Energy Market Authority (EMA). It is also the region's booking and documentation centre for projects across Southeast and South Asia, where banks, export credit agencies and development finance institutions lend from Singapore under English or Singapore law, often with disputes referred to arbitration in Singapore.
The parties and what each needs
Sponsors
Develop the project and contribute equity, sometimes with completion support. They want limited recourse, flexibility to sell down after completion and distributions as soon as covenants allow.
Project company
A special purpose vehicle that holds the licences, land rights and contracts. Its constitution and permitted business are kept narrow so that the lenders' credit analysis holds.
Senior lenders
Commercial banks, often in a syndicate with an agent and security trustee. They need predictable cash flows, robust security, information rights and control on default.
ECAs and DFIs
Export credit agencies and development finance institutions provide long tenors and political risk cover, but bring their own environmental, social and procurement standards.
Offtaker
The buyer of output under a power purchase or capacity agreement. Its credit strength and the contract terms are the foundation of the lenders' case.
EPC and O&M contractors
Build and operate the asset. Lenders want fixed price, date-certain construction with liquidated damages and performance security, and operating contracts with availability incentives.
The legal framework for project finance in Singapore
There is no single project finance statute. The structure rests on contract law, company law, insolvency law and the sector regulator's licensing rules, applied together.
- Companies Act 1967. Charges created by a Singapore company over most asset classes must be registered with ACRA. Under ACRA's charge registration guidance, registration is due within 30 days of creation for charges created in Singapore; an unregistered charge can be void against a liquidator and other secured creditors, and late registration is an offence for company officers.
- Insolvency, Restructuring and Dissolution Act 2018. In force since 30 July 2020, it governs moratoria, schemes of arrangement, judicial management and winding up. Section 440 restricts counterparties from terminating or modifying contracts merely because the company enters certain restructuring proceedings or is insolvent, which matters for both lenders and offtakers.
- Electricity Act 2001 and related energy legislation. Generating, importing and retailing electricity are licensable. Under EMA's licensing guidance, grid-connected units below 1 MW are exempt, units from 1 MW to below 10 MW need a Wholesaler Licence and units of 10 MW or more need a Generation Licence.
- Carbon Pricing Act 2018. The carbon tax rate is S$45 per tonne for 2026 and 2027, which feeds directly into the cash flow model of any fossil-fuelled asset.
- Tax. Interest paid by a Singapore borrower to non-resident lenders can attract withholding tax unless an exemption or treaty relief applies, which shapes how facilities are booked and gross-up clauses are negotiated.
Facility documents are usually based on Asia Pacific Loan Market Association templates under English or Singapore law. Disputes under project contracts are commonly referred to arbitration, often under the SIAC Rules 2025, because awards are enforceable across the region under the New York Convention. Our page on banking and finance in Singapore covers general lending mechanics.
Bankable offtake and power purchase agreements
For most projects, the offtake contract is what lenders lend against. In power, that means a power purchase agreement (PPA) or a capacity or tolling agreement. Singapore's wholesale electricity market adds a complication: unless output is contracted, it is sold at market prices, so lenders need to understand how much revenue is contracted, for how long and on what credit.
| PPA term | What lenders look for | Common sponsor pushback |
|---|---|---|
| Tenor | At least as long as the loan, with a tail after final maturity | Shorter corporate PPAs with renewal options |
| Price and indexation | Fixed or indexed tariffs that cover debt service in downside cases | Market-linked pricing to capture upside |
| Volume and curtailment | Take-or-pay or deemed generation for buyer-side curtailment | Pay-as-produced with no deemed payments |
| Termination payments | Payment on offtaker default sufficient to repay senior debt | Capped or formula-based compensation |
| Change in law | Relief for new taxes and regulation, including carbon pricing | Seller bears change in law as a business risk |
| Assignment | Free assignment by way of security and a direct agreement with the offtaker | Consent requirements and confidentiality limits |
Cross-border import projects add another layer. Singapore aims to import about 6 GW of low-carbon electricity by 2035, and EMA's staged process moves projects from Conditional Approval to Conditional Licence. Lenders will tie conditions precedent and long-stop dates to those milestones and to approvals in the host country. Our pages on renewable energy contracts and energy projects in Singapore cover the regulatory side in detail, and our post on PPAs and market permissions covers licensing questions for sellers.
The security package and how it is perfected
Project lenders take security over everything the project company owns or is entitled to, so that on default they can either sell the project as a going concern or step in to fix it. A typical Singapore security package for project finance includes:
- Share charge over the sponsors' shares in the project company, enabling a sale of the whole project without a land transfer.
- Debenture with fixed and floating charges over the project company's assets, including plant, receivables and intellectual property.
- Mortgage or charge over land rights, typically a lease or licence from a landlord such as JTC, which needs the landlord's consent and lodgement at the Singapore Land Authority.
- Assignment of project contracts, including the PPA, EPC and O&M contracts and their performance bonds and warranties, with notice to and acknowledgement from counterparties.
- Assignment of insurances, with lenders named as loss payees and co-insured.
- Account charges over all project accounts, with control arrangements with the account bank.
- Hedging receivables and any sponsor support, such as equity contribution undertakings or completion guarantees.
Perfection is where security packages fail. Charges must be registered with ACRA within the deadline under the Companies Act 1967, land security must be lodged, and notices of assignment must be served to give lenders a legal rather than merely equitable assignment. For assets outside Singapore, local law security and filings are needed in each jurisdiction.
Build a perfection tracker at signing that lists every security document, every filing, the deadline and the person responsible, including ACRA registrations, land lodgements, counterparty acknowledgements and foreign filings. Most enforcement problems trace back to a step that was nobody's job on the day of financial close.
Intercreditor arrangements and direct agreements
Intercreditor agreements
Where there is more than one class of creditor, such as senior banks, an ECA-covered tranche, mezzanine lenders and hedge counterparties, an intercreditor agreement sets the rules between them. It covers ranking of claims and security, the payment waterfall, voting thresholds for waivers and amendments, which creditors can instruct the security trustee to enforce, standstill periods before junior creditors can act, and how hedge close-out amounts rank.
The negotiation is often harder than the facility agreement. DFIs may need carve-outs for their policy requirements, hedge banks want pari passu ranking for close-out amounts, and mezzanine lenders want a real chance to cure or buy out the senior debt before enforcement.
Direct agreements and step-in
Direct agreements are signed between the lenders' agent and each key counterparty, such as the offtaker, EPC contractor, O&M contractor and landlord. The counterparty agrees to give lenders notice of the project company's default, to allow an extended cure period, and to let lenders or their nominee step in and later transfer the contract to a substitute owner. Without them, a counterparty could terminate on default and leave the lenders with security over a contract that no longer exists.
Section 440 of the IRDA adds a Singapore-specific consideration. Because it limits termination for insolvency events alone, counterparties may have fewer termination triggers than their contracts suggest, while lenders' own step-in timetable should be drafted with restructuring proceedings in mind. Our page on debt restructuring in Singapore explains the restructuring tools that may apply if a project fails.
In project finance, lenders do not lend against an asset. They lend against a web of contracts, and the security package is only as good as the weakest contract in it.
The road to financial close
- Structure and term sheet. Agree the sponsor structure, debt sizing, tenor and key commercial terms, and confirm the licensing route with the regulator.
- Lender due diligence. Lenders appoint technical, insurance, market and model advisers; legal counsel reviews licences, land rights and project contracts and reports on bankability.
- Negotiate project contracts. Revise the PPA, EPC, O&M and land documents to meet lender requirements, including assignment and direct agreement provisions.
- Document the financing. Agree the facility agreement, common terms, intercreditor agreement, hedging, accounts agreement and security documents.
- Satisfy conditions precedent. Deliver licences, consents, corporate approvals, legal opinions, insurance certificates, equity evidence and the final model and audit.
- Financial close. Sign, then perfect security within statutory deadlines, including ACRA registrations within 30 days.
- Construction drawdowns. Draw against certified progress, monitor milestones and manage change orders and delay claims with lender consent where needed.
- Completion and operations. Achieve lender completion tests, release sponsor support, move to the operating waterfall and begin covenant reporting.
How long this takes depends on the asset and the number of parties. A rooftop solar portfolio refinanced by a single bank moves far faster than a greenfield import project with ECA cover and host-country approvals. In every case, project finance in Singapore rewards sponsors who settle bankability issues in the project contracts before the lenders' advisers start their review.
Green, sustainability-linked and blended finance
Many projects now raise labelled debt. Green loans and bonds require a use of proceeds aligned with recognised principles, and sustainability-linked loans adjust the margin against performance targets. MAS runs a Green and Sustainability-Linked Loan Grant Scheme and a Sustainable Bond Grant Scheme that help offset the cost of external review.
For project finance in Singapore, labelled debt rarely changes the core structure. The security package, intercreditor terms and direct agreements remain the same; what changes is the reporting, the eligibility criteria for the use of proceeds and the consequences, usually a margin adjustment rather than a default, if targets are missed.
Blended finance, where public or philanthropic capital takes first-loss or concessional positions, is growing for transition projects in the region. MAS's Financing Asia's Transition Partnership is one example of Singapore's push in this area. Our page on green finance in Singapore covers frameworks, taxonomies and reporting.
Risks and common mistakes
Treating perfection as a post-closing formality
Singapore charges must be registered with ACRA within 30 days of creation when created in Singapore, and no extension is available for those. An unregistered charge can be void against a liquidator and other secured creditors. Land security needs landlord consent and lodgement, and contract assignments need notices. Missing any of these can leave lenders unsecured on the asset that matters most. Assign responsibility for each step before signing and confirm completion in writing.
A PPA that does not match the debt
Corporate PPAs are often shorter than the loan, priced against the market or terminable on terms that leave debt unpaid. Sponsors who sign these before lenders are involved face expensive renegotiation or reduced debt sizing. Bring lenders' counsel into PPA negotiations early, align tenor and termination payments with debt service, and make sure curtailment, change in law and carbon cost allocation are expressly dealt with.
Construction risk falling between contracts
Split procurement, with separate supply, installation and grid connection contracts, leaves gaps where no contractor is responsible for delay or underperformance. Lenders will either require a wrap, sponsor completion support or larger contingencies. Map every interface, align liquidated damages with debt service during delay and make sure performance security is assignable. Our page on construction contracts explains the main forms and risk allocation.
Ignoring withholding tax and gross-up
Interest paid by a Singapore project company to non-resident lenders may attract Singapore withholding tax unless an exemption or treaty relief applies. Standard gross-up clauses push that cost onto the borrower, which can upset the financial model. Confirm the tax status of each lender and booking office early and model the result, including the cost of any transfer of the loan to a new lender. Our post on withholding tax explains the rules.
Underestimating regulatory milestones
Licences, land consents and, for import projects, EMA's staged approvals and host-country permits all take time. If long-stop dates in the PPA, EPC contract and facility agreement do not align with realistic approval timing, the project can lose its offtake or its funding before construction starts. Build a single regulatory timetable and test each long-stop date against it.
The cross-border angle
Much project finance in Singapore concerns assets elsewhere. A typical regional deal has a project company in Indonesia, Vietnam, the Philippines or Bangladesh, a Singapore holding company, lenders booking from Singapore, English or Singapore law finance documents and SIAC arbitration. Each layer needs local security, regulatory approvals and enforceability opinions.
TRW & Co's home market illustrates the point. Power and infrastructure projects in Bangladesh often combine local licences and government support agreements with offshore financing, foreign currency risk and arbitration clauses. Singapore, Bangladesh, the UAE, the UK and China are all parties to the New York Convention, so a well-drafted arbitration clause supports enforcement across the sponsor and lender jurisdictions. Our page on international arbitration in Singapore covers seat and rules choices.
Sponsors should also consider currency convertibility and transfer restrictions in the host country, political risk insurance or DFI participation, and whether the Singapore holding company is the right place to hold equity for tax and exit purposes.
How TRW & Co helps with project finance in Singapore
We advise sponsors, project companies and lenders on project finance in Singapore and across our network. Where Singapore court representation is required, we work alongside Singapore-qualified counsel.
Bankability review
We review PPAs, EPC, O&M and land documents against lender requirements, flag gaps in termination, change in law and assignment, and propose fixes before lenders are involved.
Finance documentation
We negotiate facility, intercreditor, hedging, accounts and security documents, and coordinate conditions precedent, legal opinions and perfection steps.
Cross-border structuring
We coordinate local counsel in host countries, including Bangladesh, on security, approvals and enforceability, and align holding structures with tax and exit plans.
Distress and disputes
We advise on waivers, restructurings and step-in, and on construction and offtake disputes in arbitration, drawing on our infrastructure projects work.
See all our practice areas or contact our Singapore team at info@trw.co.
Checklist for decision-makers
- Is the licensing route confirmed with the regulator for the asset's size and grid connection?
- Does the PPA tenor, price, curtailment and termination payment support the debt?
- Are EPC liquidated damages and performance security aligned with debt service during delay?
- Are land rights secure, and will the landlord consent to security and step-in?
- Have all counterparties agreed to sign direct agreements?
- Is the intercreditor position agreed for senior, mezzanine and hedge creditors?
- Is there a perfection tracker with ACRA, land and foreign filing deadlines?
- Have withholding tax, gross-up and lender booking offices been modelled?
- Are carbon tax and change in law risks allocated in the project contracts?
- For cross-border projects, are host-country approvals, currency and enforcement risks covered?
Frequently asked questions
01What is the difference between project finance and corporate lending?
In corporate lending, the lender relies on the borrower group's overall balance sheet. In project finance, the borrower is a single-purpose company and lenders rely mainly on the project's cash flows and contracts, with limited or no recourse to sponsors after completion. That is why lenders scrutinise the offtake agreement, construction and operating contracts, licences and land rights, and why they take security over everything the project company owns and sign direct agreements with its key counterparties.
02What security do project lenders take in Singapore?
Typically a share charge over the project company, a debenture with fixed and floating charges, a mortgage or charge over land rights with the landlord's consent, assignments of the PPA, EPC and O&M contracts, assignments of insurances, charges over project accounts and assignment of hedging receivables. Charges created in Singapore must be registered with ACRA within 30 days, land security lodged with SLA, and notices of assignment served on counterparties.
03What is a direct agreement?
A direct agreement is a contract between the lenders, usually through their agent or security trustee, and a key project counterparty such as the offtaker, EPC contractor or landlord. The counterparty agrees to notify lenders of the project company's defaults, allow extra time to cure, permit lenders or their nominee to step in and transfer the contract to a new owner. It protects lenders from losing the contract that underpins their security.
04Why does an intercreditor agreement matter?
When a project has several classes of creditor, such as senior banks, ECA-covered lenders, mezzanine lenders and hedge counterparties, the intercreditor agreement decides who ranks first, how cash is applied, who can vote on waivers and who can instruct enforcement. Without clear rules, creditors can block each other at the moment decisive action is needed. Juniors typically accept standstill periods in exchange for cure and purchase rights.
05Does a solar project in Singapore need an EMA licence to be financed?
It depends on unit size and grid connection. EMA's guidance exempts grid-connected units below 1 MW, requires a Wholesaler Licence for units from 1 MW to below 10 MW and a Generation Licence for units of 10 MW or more. Lenders will want the licence or exemption position confirmed as a condition precedent, along with the site lease, landlord consent and the PPA or lease with the host.
06Is withholding tax payable on interest to foreign project lenders?
It can be. Interest paid by a Singapore borrower to non-resident lenders may attract Singapore withholding tax unless an exemption or treaty relief applies. Facility agreements usually contain gross-up clauses that shift the cost to the borrower, so the tax status of each lender and its booking office should be confirmed and modelled before signing. Transfer clauses should also address whether a new lender that cannot claim the same relief is entitled to a gross-up.
07Why do regional projects choose Singapore arbitration?
Singapore is a neutral, established seat with a supportive court system, and SIAC administers arbitrations under its 2025 Rules. Awards made in Singapore are enforceable in other New York Convention states, including Bangladesh, the UAE, the UK and China. For projects with sponsors, lenders and assets in several countries, that enforceability is a key reason to choose Singapore arbitration in project and finance documents.
Sources and official materials
- ACRA: Registering a charge — 30-day registration and consequences of non-registration
- Insolvency, Restructuring and Dissolution Act 2018 — Restructuring tools and ipso facto restriction
- Electricity Act 2001 — Licensing of generation, import and retail
- EMA: Which licence should I apply for to generate electricity — Licence thresholds by unit size
- EMA: Regional power grids and electricity imports — 6 GW import target and staged approvals
- MAS: Sustainable finance for capital markets and banking — Green loan and sustainable bond grant schemes
- NEA: Carbon tax — Carbon tax rates and thresholds
- SIAC Rules 2025 — Arbitration rules for project disputes
General information only, current as at 20 October 2026. It is not legal advice and does not create a lawyer–client relationship. Singapore law and regulatory practice change; check current official sources and take advice on the facts of your matter.



